The deadline for 2025 federal tax returns was Wednesday, April 15, 2026; returns on extension are due Thursday, October 15, 2026, and 2026 returns are due Thursday, April 15, 2027. If you missed a deadline, there is no cutoff for filing a past-due return: the IRS generally asks for the last six years (Policy Statement 5-133), and filing now stops the 5%-a-month failure-to-file penalty even if you can't pay anything yet. Refunds are the one thing with an expiration date: unclaimed 2022 refunds lapsed on April 15, 2026, and 2023 refunds lapse on April 15, 2027.
Key takeaways:
Tax deadlines for 2026: April 15, 2026 for 2025 returns and payments; October 15, 2026 for extended 2025 returns; January 15, 2027 for the last 2026 estimated payment; April 15, 2027 for 2026 returns
How far back to file: no legal limit, but the IRS generally enforces only the last six years; free wage and income transcripts in your IRS Online Account cover the current and nine prior tax years
Penalties: failure-to-file 5% of unpaid tax per month (max 25%), with a $525 minimum for 2025 returns filed more than 60 days late; failure-to-pay 0.5% per month; interest 7% in the third and fourth quarters of 2026, compounded daily
Penalty relief: First Time Abate removes the penalties for one year with a clean three-year record (you request it for 2024 and earlier); eligible late 2025 returns now get the IRS's Automatic Exemption from Penalty without a request
Can't pay: a balance of $50,000 or less qualifies for an IRS Simple Payment Plan with no financial statement ($29 setup online with direct debit); a balance under $100,000 can use a free 180-day plan
E-filing for 2026 returns opens when the IRS starts the 2027 filing season, usually in late January; the IRS hasn't announced the 2027 date yet.
It's not too late to file a 2025 return that missed April 15, 2026: the IRS accepts past-due returns indefinitely. Without an extension, though, the return is already late, and three things change once a deadline passes. The failure-to-file penalty runs 5% of the unpaid tax per month (4.5% when the late-payment penalty also applies), up to 25%. Once the return is more than 60 days late, the penalty is at least $525 or the full tax due, whichever is less. And interest has compounded daily since April 15. Since mid-September 2026, an unextended 2025 return's late-filing penalty has been at its cap, so each additional month now adds the 0.5% payment penalty plus interest.
Enter your balance and how late you are to see both §6651 penalties — and what filing on time would have saved.
$
6 mo
Estimated penalties
$2,550
Filing on time would have cut this to $300 — the $2,250 failure-to-file share is pure late-filing cost.
Failure to file (offset to 4.5%/mo)$2,250
Failure to pay (0.5%/mo)$300
Share of your balance25.5%
IRC §6651 math from the article's examples: 5%/month failure-to-file offset by the 0.5%/month failure-to-pay, 25% caps, and the 60-day minimum penalty. IRS interest accrues on top and isn't included; an approved installment agreement halves the failure-to-pay rate to 0.25%/month only if the return was filed on time.
With the defaults, a $10,000 balance on a 2025 return filed six months late (mid-October 2026) carries a $2,250 failure-to-file penalty (five months at 4.5%, the 25% cap net of the payment penalty) plus a $300 failure-to-pay penalty (six months at 0.5%): $2,550 before interest. Filing on time and paying late would have cost only the $300.
Those numbers assume no relief. If your 2022, 2023 and 2024 returns were filed on time with no penalties (an estimated-tax penalty doesn't count), the IRS's Automatic Exemption from Penalty, introduced in July 2026, skips the failure-to-file and failure-to-pay penalties on a late 2025 return automatically; you owe the tax and interest only.
You can file a return for any year, no matter how long ago. To be treated as in "filing compliance" for a payment plan, a loan, or to stop enforcement, the IRS generally wants the most recent six years on file (IRS Policy Statement 5-133).
Rule
Detail
Time limit to file
None. You can file any year
Years to file for compliance
Generally the last 6 years (IRS Policy Statement 5-133)
Time limit to claim a refund
3 years from the original due date (IRC §6511); 2023 refunds expire April 15, 2027
E-file window in 2026
2025, 2024 and 2023 returns; 2022 and earlier must be mailed
Failure-to-file penalty
5% of unpaid tax per month, up to 25%
Failure-to-pay penalty
0.5% of unpaid tax per month, up to 25%
Minimum late filing penalty
Lesser of 100% of the tax due or $525 for 2025 returns more than 60 days late ($510 for 2024 returns, $485 for 2023, $450 for 2022)
Interest on unpaid tax
Federal short-term rate + 3% = 7% for Q3 and Q4 2026, compounded daily
Payment plan thresholds
$50,000 or less for a Simple Payment Plan; under $100,000 for a free 180-day plan
Offer in Compromise
Settle for less than owed if you qualify ($205 application fee)
Legal basis: IRC §6511 (refund limitations), IRC §6651 (penalties), IRC §6601 (interest), IRS Policy Statement 5-133 (six-year filing norm), Form 9465 (installment agreement), Form 656 (Offer in Compromise)
Save this cheat sheet: the deadlines, refund windows, penalties, and payment plans in one image.
W-2 employees have federal and state taxes withheld from every paycheck. By tax time, most of them are close to breaking even or due a refund. Self-employed individuals have nothing withheld. Their entire tax bill, income tax plus 15.3% self-employment tax, comes due at once.
The IRS expects self-employed individuals to make quarterly estimated tax payments. But when you're busy running a business, those quarterly deadlines (April 15, June 15, September 15, January 15) slip by. Miss a couple of quarters, and the year-end bill becomes intimidating.
Freelancers don't always know what they'll earn in a given year. A great Q4 can push you into a higher tax bracket and create a large unexpected bill. A slow Q1 might tempt you to skip estimated payments that turn out to be needed.
The most dangerous pattern: you owe taxes for Year 1, don't file, and then feel too anxious to file Year 2 because Year 1 is still outstanding. Each year adds to the pile. Penalties and interest accumulate. The problem that started as a $3,000 tax bill becomes a $15,000 problem over three or four years.
The good news: The IRS would rather work with you than against you. Filing, even years late, puts you on a path to resolution.
You can file a federal return for any past year, but most people only need the last six. IRS Policy Statement 5-133 (Internal Revenue Manual 1.2.1.6.18) says all delinquent returns a taxpayer submits "will be accepted," and that its enforcement criteria "normally" result in pursuing unfiled returns "for not more than six (6) years," with anything longer needing a manager's approval. The IRS treats a taxpayer who has filed the most recent six years as being in filing compliance for a payment plan, an Offer in Compromise, or to release enforced collection. A revenue officer can require more years when the facts justify it (large potential liability, business returns, an open investigation), but six is the working norm.
Check your records or call the IRS (1-800-829-1040) to find out which years have unfiled returns. You can also:
Pull a wage and income transcript for each missing year: it lists the W-2, 1099, 1098 and 5498 data the IRS received, and the Online Account covers the current and nine prior tax years. By mail, file Form 4506-T and check the box on line 8
If the IRS has filed a Substitute for Return (SFR) on your behalf, your transcript will show it. SFRs are filed when the IRS has income information (from 1099s and W-2s sent by your clients and employers) but no return from you. Before assessing the tax, the IRS mails Notice CP3219N, a 90-day letter that gives you 90 days to file your own return or petition the Tax Court. SFRs are almost always worse for you than filing yourself because the IRS claims no deductions or credits on your behalf.
Income records:1099-NEC forms, 1099-MISC, 1099-K, W-2s, bank statements showing business deposits
Expense records: Bank and credit card statements, receipts, mileage logs, home office measurements
Prior year returns: If you filed some years but not others, prior returns help with consistency and carryforward items
Missing documents? Request wage and income transcripts from the IRS for each year. These show all reported income. For expenses, use bank and credit card statements as backup documentation.
This is critical: you must use the tax forms and rules for the year you're filing. A 2022 tax return uses 2022 forms, 2022 tax rates, and 2022 standard deduction amounts.
The 2025 single standard deduction is $15,750 after the One Big Beautiful Bill Act raised it; the 2026 amount is $16,100 (IRS Rev. Proc. 2025-32). The Social Security wage base, the cap on the 12.4% Social Security portion of self-employment tax, rose to $184,500 for 2026 from $176,100 in 2025.
Schedule 1: Additional income and adjustments (deductible half of SE tax)
Any other applicable schedules (Schedule A if itemizing, Schedule D for capital gains, etc.)
Claim every deduction you're entitled to. Business expenses, home office deduction, vehicle expenses, health insurance premiums, and retirement contributions all reduce your tax liability. Use our Self-Employment Tax Calculator to estimate what you owe for each year, and the 1099 Tax Calculator to understand your total liability.
E-filing: In 2026, IRS e-file accepts 2025, 2024 and 2023 individual returns, so tax software can e-file those three years (IRS Modernized e-File). Returns for 2022 and earlier must be filed on paper.
Filing by mail: Print and sign each return, then mail it to the appropriate IRS address for your state (the address varies by year and state; check the instructions for each year's Form 1040). If an IRS notice asked for the return, send it to the address on the notice instead.
File the most recent years first if you're filing multiple years. The IRS prioritizes recent compliance, and having the most recent years on file shows good faith.
This is the single most important piece of advice in this guide: file even if you can't pay the full amount. The failure-to-file penalty (5% per month) is ten times worse than the failure-to-pay penalty (0.5% per month). Filing the return stops the more expensive penalty from accruing.
Rate: 5% of unpaid tax for each month (or partial month) the return is late
Maximum: 25% of unpaid tax
Minimum: If your return is more than 60 days late, the minimum penalty is the lesser of the tax due or a dollar floor set by the year the return was due: $525 for returns due in 2026 (tax year 2025), $510 for returns due in 2025, $485 for those due in 2024 and $450 for those due in 2023, per the IRS failure-to-file penalty page
Combined with failure-to-pay: If both penalties apply in the same month, the failure-to-file penalty is reduced by the failure-to-pay penalty. The combined maximum is still 5% per month (4.5% file + 0.5% pay).
Rate: 0.5% of unpaid tax for each month (or partial month) it remains unpaid
Maximum: 25% of unpaid tax
Reduced rate: While an approved payment plan is in effect, the rate drops to 0.25% per month, but only for individuals who filed that return on time; a back return filed late keeps the 0.5% rate
Increased rate: If you don't pay within 10 days of an IRS notice of intent to levy, the rate rises to 1% per month
Rate: Federal short-term rate + 3%, compounded daily
Current rate: 7% for the fourth quarter of 2026 (October through December), unchanged from the third quarter; it was 6% in the second quarter. The IRS resets this rate every quarter, and it has ranged 6%–8% since 2023.
Key fact: Interest accrues from the original due date of the return, not from the date you file. This means interest is accumulating right now on any unfiled returns where tax is owed.
No waiver: Unlike penalties, the IRS generally cannot waive interest. It accrues by law, although interest on a penalty disappears when the penalty is removed.
Here's what happens to a $5,000 tax debt if you don't file or pay:
Time Period
Failure-to-File
Failure-to-Pay
Interest (7%)
Total Owed
1 month late
$225
$25
$29
$5,279
5 months late
$1,125 (max)
$125
$148
$6,398
1 year late
$1,125 (max)
$300
$363
$6,788
3 years late
$1,125 (max)
$900
$1,168
$8,193
5 years late
$1,125 (max)
$1,250 (max)
$2,096
$9,471
Note: The failure-to-file column is net of the payment penalty for the months both apply (4.5% a month), which is why it caps at $1,125 rather than $1,250. Interest is on the tax only, at a flat 7% compounded daily; the IRS also charges interest on the failure-to-file penalty from the return's due date, so real balances run somewhat higher.
The longer you wait, the more it costs, but most of the penalty damage happens in the first five months, when the failure-to-file penalty maxes out. After that, it's mostly interest accumulation.
If you can pay your full balance within 180 days and owe less than $100,000 in combined tax, penalties and interest, the IRS offers a short-term payment plan with no setup fee. Interest and the failure-to-pay penalty continue to accrue during the 180 days.
An OIC lets you settle your tax debt for less than the full amount owed. The IRS considers:
Your ability to pay (income and assets)
Your expenses (allowed living expenses)
Your future earning potential
Qualifying is difficult. In fiscal year 2025 the IRS accepted 5,464 of the 38,797 offers it received, about one in seven (IRS Data Book 2025, Table 4-1). You must be current on all filing requirements and estimated tax payments. There's a $205 application fee plus an initial payment (20% of the offer for a lump-sum offer); low-income applicants skip both. Our offer in compromise guide shows how Form 433-A (OIC) turns your assets and income into a minimum offer.
The IRS Fresh Start Initiative expanded OIC eligibility by allowing the IRS to consider only one year of future income (for lump-sum offers) or two years (for periodic payment offers), instead of four or five years under prior guidelines.
If you genuinely cannot pay anything, because your income only covers basic living expenses, you can request CNC status. The IRS temporarily stops collection activity, but:
Interest and penalties continue to accrue
The IRS reviews your financial situation periodically
First Time Abate removes the failure-to-file and failure-to-pay penalties for one tax year when you filed the same type of return on time for the three prior years and no penalties were assessed in them (an estimated-tax penalty doesn't count). For back years (2024 and earlier), you have to request it: call the number on your IRS notice or file Form 843 to request penalty abatement. In a run of unfiled years, it usually helps only the first one, because every later year has a late return inside its three-year lookback.
For 2025 returns processed since summer 2026, the IRS applies the same test automatically as the Automatic Exemption from Penalty and sends a notice when it does (IRS administrative penalty relief). Interest on the unpaid tax still applies.
You can also request penalty relief for "reasonable cause": serious illness, natural disaster, death in the family, or reliance on incorrect professional advice.
When you don't file, the IRS may eventually file a Substitute for Return on your behalf. An SFR uses the income information reported to the IRS (from your clients' 1099s, your banks' 1099-INTs, etc.) and calculates your tax with:
No business deductions: The IRS won't claim your home office, vehicle expenses, supplies, or other Schedule C deductions
No favorable filing status: SFRs typically use "single" or "married filing separately"
No credits: No earned income credit, child tax credits, or education credits
No adjustments: No deductible half of self-employment tax, no IRA deductions, no HSA deductions
The result: an SFR almost always shows a much higher tax liability than what you'd owe if you filed yourself. If the IRS has filed an SFR for any of your missing years, you can (and should) file your own return to replace it. Your actual return will supersede the SFR.
Here's a detail that costs people thousands of dollars: if the IRS owes YOU money, you only have 3 years from the original due date to claim it (IRC §6511).
For example:
2022 return: the refund window closed on April 15, 2026. The IRS estimated that about $1.2 billion in 2022 refunds went unclaimed, with a median of $686 (IR-2026-37)
2023 return (due April 15, 2024): refund claim deadline is April 15, 2027
If you had expenses that exceeded your income in a given year, or you're entitled to refundable credits, filing late can still put money in your pocket, but only if you're within the 3-year window. After that, the refund is forfeited permanently. The IRS can also hold a refund until missing later-year returns are filed, and it applies any refund to federal or state tax you still owe.
For self-employed individuals: Even if you owe tax for most years, check each year individually. You might have had a slow year where deductions exceeded income, making you eligible for a refund. File those years first to capture the refund before the deadline expires.
Filing back taxes isn't just about settling old debts. Being "in compliance" with the IRS affects several other areas:
Passport renewal/application: The IRS can certify your tax debt to the State Department if you owe more than $66,000 (the seriously delinquent tax debt threshold for 2026 under IRC §7345, adjusted yearly for inflation), which can result in passport denial or revocation
Mortgage applications: Lenders typically require two years of filed tax returns
Business loans and SBA loans: Require filed returns for all open years
Installment agreements and OICs: You must file all required returns before the IRS will consider a payment plan
Social Security credits: If you don't file self-employment returns, you don't receive credit for those earnings toward Social Security retirement benefits
Statute of limitations on audits: The IRS's 3-year audit window doesn't start until you file. If you never file, the IRS can audit that year forever
The failure-to-file penalty is 10x the failure-to-pay penalty. File the return even if you can pay nothing. It stops the 5% monthly penalty and starts the clock on the statute of limitations.
When you're anxious about back taxes, it's tempting to rush through the returns. But skipping legitimate deductions means overpaying. Take the time to reconstruct your business expenses from bank statements. Every deduction reduces both income tax and self-employment tax.
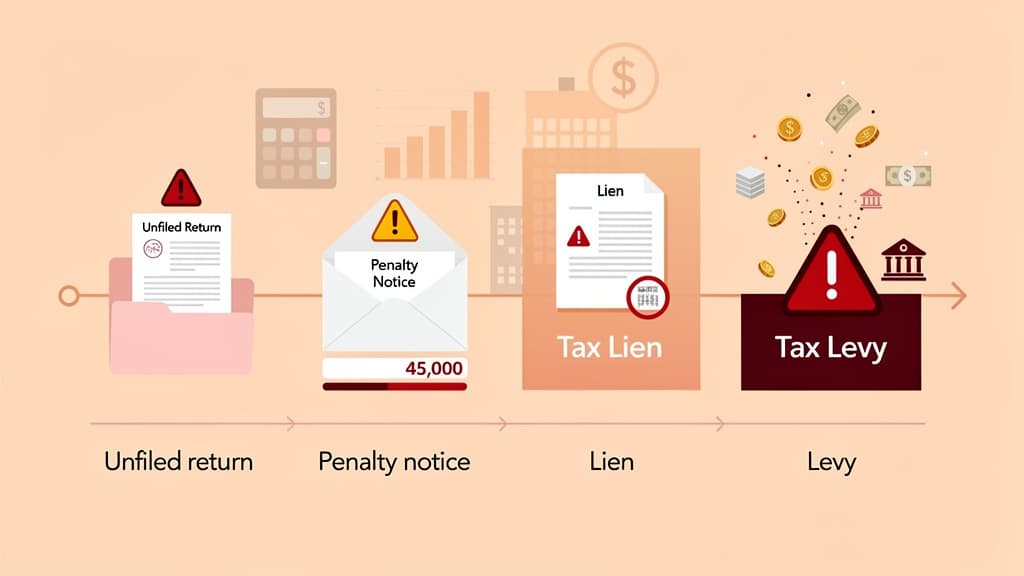
IRS notices escalate in severity. The progression typically goes: CP14 (balance due) → CP501 (reminder) → CP503 (urgent) → CP504 (intent to levy) → LT11/Letter 1058 (final notice of levy). Responding early gives you more options.
Some companies charge thousands of dollars upfront to "negotiate" with the IRS. Before paying anyone, file your returns yourself (or with a CPA/EA). Many people discover their actual liability is manageable once deductions are applied. You don't need a negotiator if you can set up a $200/month installment agreement online for a $29 setup fee.
If the IRS owes you a refund for any year, the clock is ticking. Prioritize filing any year where you might be owed money and the 3-year window is about to close.
Rebuilding old years from bank statements is the slow part of filing back taxes, and it's avoidable going forward. Jupid connects to your bank accounts and categorizes every transaction automatically with 95.9% accuracy, so this year's Schedule C numbers are ready when April 15, 2027 arrives instead of being reconstructed months later. The AI accountant works in WhatsApp and iMessage: ask how much profit your business made last quarter and get an answer from your real transactions in seconds. Try Jupid
Filing back taxes feels overwhelming, but the process is straightforward once you start: gather documents, use the correct year's forms, claim every deduction, and file. The IRS offers multiple payment options for balances you can't pay in full.
The most expensive decision is doing nothing. Every month of inaction adds penalties and interest, and keeps you locked out of loans, payment plans, and the peace of mind that comes with being in compliance.
Disclaimer
This article provides general information about filing back taxes and should not be considered tax or legal advice. Penalty calculations, interest rates, and IRS program eligibility depend on your specific circumstances. The IRS Fresh Start Initiative criteria and payment plan terms are subject to change. For advice specific to your situation, consult with a qualified tax professional, enrolled agent, or tax attorney.
Fintech CEO with 10+ years building accounting and financial technology products. Previously co-founded and scaled an AI-powered accounting platform to $30M revenue and 100K+ business users, achieving 30,000 customers per accountant through automation — recognized by CNBC as a top fintech company. Holds a Master's in Management Information Systems. At Jupid, he leads the development of AI-native bookkeeping, tax, and compliance tools designed for freelancers and small business owners.